Publications
State-by-State Tax Expenditure Reports
• By ITEP Staff
Below is a list of tax expenditure reports published in the states.
The 5 Biggest State Tax Cuts for Millionaires this Year
• By Dylan Grundman O'Neill, Aidan Davis
Some states continue to hand out huge tax cuts to millionaires. The five largest tax cuts this year will cost states a total of $2.2 billion per year once fully implemented.
States Should Move Quickly to Chart Their Own Course on SALT Deductions
• By Dylan Grundman O'Neill, Nick Johnson
While a federal SALT cap is hotly debated, capping deductibility at $10,000 was an unambiguously good idea at the state level. States would be smart to stick with the current cap or, better yet, go even farther and repeal SALT deductions outright. Going along with a higher federal SALT cap would double down on a regressive tax cut that will mostly benefit a small number of relatively wealthy state residents and cost states significant revenue.
Analysis of Tax Provisions in the Trump Megabill as Signed into Law: National and State Level Estimates
• By Steve Wamhoff, Carl Davis, Joe Hughes, Jessica Vela
President Trump has signed into law the tax and spending “megabill” that largely favors the richest taxpayers and provides working-class Americans with relatively small tax cuts that will in many cases be more than offset by Trump's tariffs.
Analysis of Tax Provisions in the House Reconciliation Bill: National and State Level Estimates
• By Carl Davis, Jessica Vela, Joe Hughes, Steve Wamhoff
The poorest fifth of Americans would receive 1 percent of the House reconciliation bill's net tax cuts in 2026 while the richest fifth of Americans would receive two-thirds of the tax cuts. The richest 5 percent alone would receive a little less than half of the net tax cuts that year.
Trump 2025 Tax Law: Research and Resources
• By ITEP Staff
Want to know more about the tax and spending megabill that President Trump recently signed into law? We've got you covered.
Sharp Turn in Federal Policy Brings Significant Risks for State Tax Revenues
• By Carl Davis
Summary The new presidential administration and Congress have indicated that they intend to bring about a dramatic federal retreat in funding for health care, food assistance, education, and other services that will push more of the responsibility for providing these essential services to the states. Meeting these new obligations would be a challenging task for […]
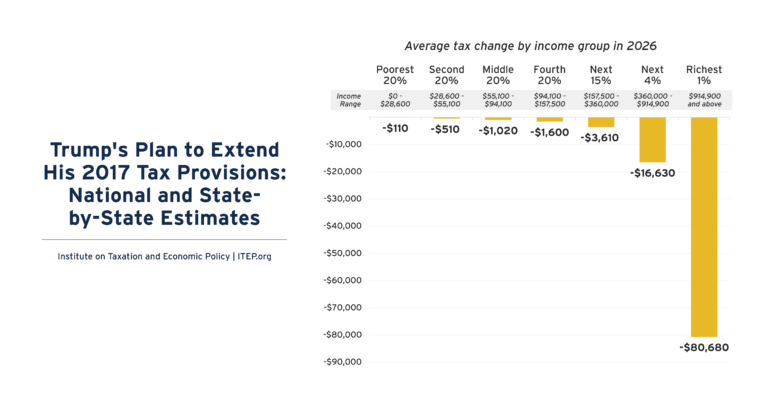
Trump’s Plan to Extend His 2017 Tax Provisions: Updated National and State-by-State Estimates
• By Steve Wamhoff
Trump’s plan to make most of the temporary provisions of his 2017 tax law permanent would disproportionately benefit the richest Americans. This includes all major provisions except the $10,000 cap on deductions for state and local taxes (SALT) paid.

Extending Temporary Provisions of the 2017 Trump Tax Law: Updated National and State-by-State Estimates
• By Steve Wamhoff
The TCJA Permanency Act would make permanent the provisions of the Tax Cuts and Jobs Act of 2017 that are set to expire at the end of 2025. The legislation would disproportionately benefit the richest Americans. Below are graphics for each state that show the effects of making TCJA permanent across income groups. See ITEP’s […]
Tax Payments by Undocumented Immigrants
• By ITEP Staff
Undocumented immigrants paid $96.7 billion in federal, state, and local taxes in 2022. Providing access to work authorization for undocumented immigrants would increase their tax contributions both because their wages would rise and because their rates of tax compliance would increase.
Improving Refundable Tax Credits by Making Them Immigrant-Inclusive
• By Emma Sifre, Marco Guzman
Undocumented immigrants who work and pay taxes but don't have a valid Social Security number for either themselves or their children are excluded from federal EITC and CTC benefits. Fortunately, several states have stepped in to ensure undocumented immigrants are not left behind by the gaps in the federal EITC and CTC. State lawmakers should continue to ensure that immigrants who are otherwise eligible for these tax credits receive them.
America Used to Have a Wealth Tax: The Forgotten History of the General Property Tax
• By Carl Davis, Eli Byerly-Duke
Over time, broad wealth taxes were whittled away to become the narrower property taxes we have today. These selective wealth taxes apply to the kinds of wealth that make up a large share of middle-class families’ net worth (like homes and cars), but usually exempt most of the net worth of the wealthy (like business equity, bonds, and pooled investment funds).The rationale for this pared-back approach to wealth taxation has grown weaker in recent decades…
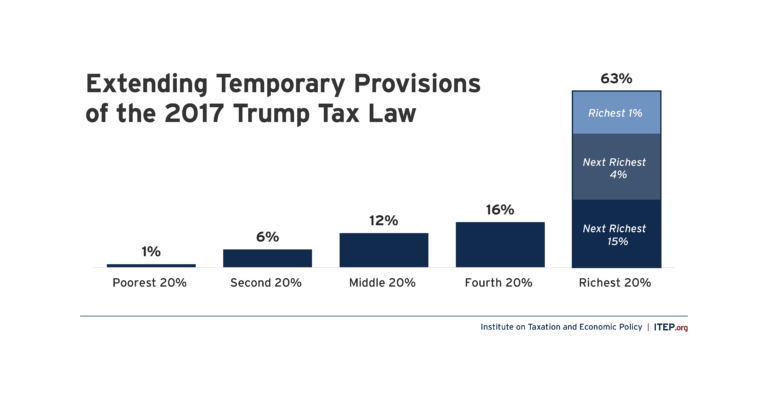
Extending Temporary Provisions of the 2017 Trump Tax Law: National and State-by-State Estimates
• By Joe Hughes, Matthew Gardner, Steve Wamhoff
The push by Congressional Republicans to make the provisions of the 2017 Tax Cuts and Jobs Act permanent would cost nearly $300 billion in the first year and deliver the bulk of the tax benefits to the wealthiest Americans.
Tax Avoidance Continues to Fuel School Privatization Efforts
• By Carl Davis
Wealthy families are overwhelmingly the ones using school voucher tax credits to opt out of paying for public education and other public services and to redirect their tax dollars to private and religious institutions instead. Most of these credits are being claimed by families with incomes over $200,000.
State Child Tax Credits and Child Poverty: A 50-State Analysis
• By Aidan Davis
Regardless of future Child Tax Credit developments at the federal level, state policies can supplement the federal credit to deliver additional benefits to children and families. State credits can be specifically tailored to meet the needs of local populations while also producing long-term benefits for society as a whole
State Income Taxes and Racial Equity: Narrowing Racial Income and Wealth Gaps with State Personal Income Taxes
• By Carl Davis, Jessica Schieder, Marco Guzman
10 state personal income tax reforms that offer the most promising routes toward narrowing racial income and wealth gaps through the tax code.
Taxes and Racial Equity: An Overview of State and Local Policy Impacts
• By ITEP Staff
Historic and current injustices, both in public policy and in broader society, have resulted in vast disparities in income and wealth across race and ethnicity. Employment discrimination has denied good job opportunities to people of color. An uneven system of public education funding advantages wealthier white people and produces unequal educational outcomes. Racist policies such as redlining and discrimination in lending practices have denied countless Black families the opportunity to become homeowners or business owners,…
Comparing Flat-Rate Income Tax Options for Alaska
• By Carl Davis
Alaska lawmakers are facing an unprecedented fiscal crisis. The state is more dependent than any other on oil tax and royalty revenues but declines in oil prices and production levels have sapped much of the vitality of these revenue sources. One way of diversifying the state’s revenue stream and narrowing the yawning gap between state revenues and expenses would be to reinstitute a statewide personal income tax. Alaska previously levied such a tax until 1980.…
State Taxation of Capital Gains: The Folly of Tax Cuts & Case for Proactive Reforms
• By Marco Guzman
The federal tax system and every state treat income from capital gains more favorably than income from work. Preferential capital gains tax treatment includes exclusions and seldom-discussed provisions like deferral and stepped-up basis, as well as more direct tax subsidies for profits realized from local investments and, in some instances, from investments around the world. This policy brief explains state capital gains taxation, examines the flaws in state capital gains tax breaks, and proposes reform…
State Options to Shore up Revenues and Improve Tax Codes amid Pandemic
• By Dylan Grundman O'Neill, Meg Wiehe
The COVID-19 pandemic is an extraordinarily challenging time, as we see harm and struggle affecting the vast majority of our families, businesses, public services, and economic sectors. No one will be unaffected by the crisis, and everyone has a stake in the recovery and faces tough decisions. In the world of state fiscal policy, where revenue shortfalls are likely to be far bigger than can be filled by the initial $150 billion in federal aid…
State Itemized Deductions: Surveying the Landscape, Exploring Reforms
• By Carl Davis
State itemized deductions are generally patterned after federal law, though nearly every state makes significant changes to the menu of deductions available or the extent to which those deductions are allowed. This report summarizes the key details of each state’s itemized deduction policies and discusses various options for reforming those deductions with a focus on lessening their regressive impact and reducing their cost to state budgets.
State Tax Codes as Poverty Fighting Tools: 2019 Update on Four Key Policies in All 50 States
• By Aidan Davis
This report presents a comprehensive overview of anti-poverty tax policies, surveys tax policy decisions made in the states in 2019 and offers recommendations that every state should consider to help families rise out of poverty. States can jump start their anti-poverty efforts by enacting one or more of four proven and effective tax strategies to reduce the share of taxes paid by low- and moderate-income families: state Earned Income Tax Credits, property tax circuit breakers,…
The Case for Extending State-Level Child Tax Credits to Those Left Out: A 50-State Analysis
• By Aidan Davis, Meg Wiehe
As of 2017, 11.5 million children in the United States were living in poverty. A national, fully-refundable Child Tax Credit (CTC) would effectively address persistently high child poverty rates at the national and state levels. The federal CTC in its current form falls short of achieving this goal due to its earnings requirement and lack of full refundability. Fortunately, states have options to make state-level improvements in the absence of federal policy change. A state-level…
A Simple Fix for a $17 Billion Loophole: How States Can Reclaim Revenue Lost to Tax Havens
• By Richard Phillips
Enacting Worldwide Combined Reporting or Complete Reporting in all states, this report calculates, would increase state tax revenue by $17.04 billion dollars. Of that total, $2.85 billion would be raised through domestic Combined Reporting improvements, and $14.19 billion would be raised by addressing offshore tax dodging (see Table 1). Enacting Combined Reporting and including known tax havens would result in $7.75 billion in annual tax revenue, $4.9 billion from income booked offshore.
Who Pays and Why It Matters | MECEP Policy Insights Conference Keynote Address
• By Aidan Davis
States have broad discretion in how they secure the resources to fund education, health care, infrastructure, and other priorities important to communities and families. Aidan Davis with the Institute on Taxation and Economic Policy will offer a national perspective on state-level approaches to funding public investments and the implications of those approaches on tax fairness and revenue adequacy, and their economic outcomes. She’ll also provide insight on what’s in store for 2019 among the states.
Institute on Taxation
and Economic Policy
ITEP is a non-profit, non-partisan tax policy organization. We conduct rigorous analyses of tax and economic proposals and provide data-driven recommendations to shape equitable and sustainable tax systems.
Subscribe to ITEP Emails
Tax research and policy news in your inbox.
Promote Fair Tax Policy
Your gift to ITEP promotes tax justice. With your help, we do research that supports taxing millionaires and billionaires, taxing big corporations and raising revenue for the things our people, our communities and our planet need.
Together, we can create a country with more economic justice, more racial justice, more climate justice… and more tax justice.