Publications
State-by-State Tax Expenditure Reports
• By ITEP Staff
Below is a list of tax expenditure reports published in the states.
The Potential of Local Child Tax Credits to Reduce Child Poverty
• By Kamolika Das, Aidan Davis, Galen Hendricks, Rita Jefferson
Local governments have a critical role to play in reducing child poverty. Local Child Tax Credits could provide large tax cuts to families at the bottom of the income scale, lessening the overall regressivity of state and local tax systems.
Sales Tax Holidays Miss the Mark When it Comes to Effective Sales Tax Reform
• By Miles Trinidad
Sales tax holidays are often marketed as relief for everyday families, but they do little to address the deeper inequities of regressive sales taxes. In 2025, 18 states offer these holidays at a collective cost of $1.3 billion.
Anti-Tax Revolts Backfire: What We’ve Learned from 50 Years of Property Tax Limits
• By Rita Jefferson
Across-the-board property tax cuts create less fair local tax systems in the long run. State legislators and local governments should prioritize the residents who can least afford their property taxes, not the residents and businesses who can.
Analysis of Tax Provisions in the Trump Megabill as Signed into Law: National and State Level Estimates
• By Steve Wamhoff, Carl Davis, Joe Hughes, Jessica Vela
President Trump has signed into law the tax and spending “megabill” that largely favors the richest taxpayers and provides working-class Americans with relatively small tax cuts that will in many cases be more than offset by Trump's tariffs.
Analysis of Tax Provisions in the House Reconciliation Bill: National and State Level Estimates
• By Carl Davis, Jessica Vela, Joe Hughes, Steve Wamhoff
The poorest fifth of Americans would receive 1 percent of the House reconciliation bill's net tax cuts in 2026 while the richest fifth of Americans would receive two-thirds of the tax cuts. The richest 5 percent alone would receive a little less than half of the net tax cuts that year.
Trump 2025 Tax Law: Research and Resources
• By ITEP Staff
Want to know more about the tax and spending megabill that President Trump recently signed into law? We've got you covered.
A Revenue Analysis of Worldwide Combined Reporting in the States
• By Carl Davis, Matthew Gardner, Michael Mazerov
Universal adoption of mandatory worldwide combined reporting would boost state corporate income tax revenues by roughly 14 percent. Thirty-eight states and the District of Columbia would experience revenue increases totaling $19.1 billion.
The (Mostly Untapped) Power of Local Income Taxes
• By Rita Jefferson
Local income taxes can be an important progressive revenue raiser, as they ask more of higher-income households and are connected to ability to pay. They can raise substantial revenue to fund key public services to make cities and regions better off.
Trump’s Plan to Extend His 2017 Tax Provisions: Updated National and State-by-State Estimates
• By Steve Wamhoff
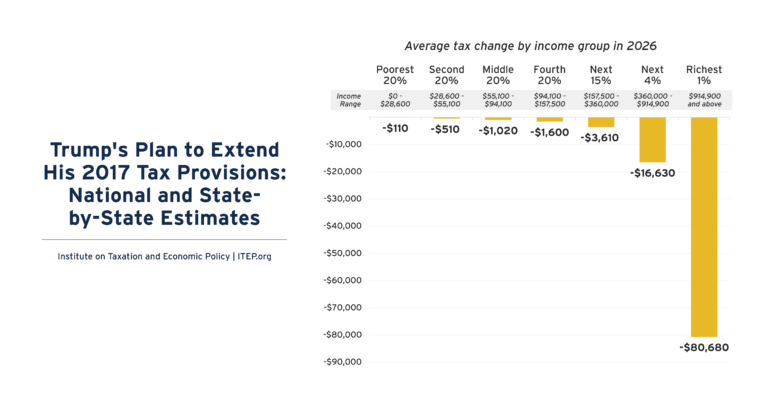
Trump’s plan to make most of the temporary provisions of his 2017 tax law permanent would disproportionately benefit the richest Americans. This includes all major provisions except the $10,000 cap on deductions for state and local taxes (SALT) paid.

Extending Temporary Provisions of the 2017 Trump Tax Law: Updated National and State-by-State Estimates
• By Steve Wamhoff
The TCJA Permanency Act would make permanent the provisions of the Tax Cuts and Jobs Act of 2017 that are set to expire at the end of 2025. The legislation would disproportionately benefit the richest Americans. Below are graphics for each state that show the effects of making TCJA permanent across income groups. See ITEP’s […]
Tax Payments by Undocumented Immigrants
• By ITEP Staff
Undocumented immigrants paid $96.7 billion in federal, state, and local taxes in 2022. Providing access to work authorization for undocumented immigrants would increase their tax contributions both because their wages would rise and because their rates of tax compliance would increase.
Improving Refundable Tax Credits by Making Them Immigrant-Inclusive
• By Emma Sifre, Marco Guzman
Undocumented immigrants who work and pay taxes but don't have a valid Social Security number for either themselves or their children are excluded from federal EITC and CTC benefits. Fortunately, several states have stepped in to ensure undocumented immigrants are not left behind by the gaps in the federal EITC and CTC. State lawmakers should continue to ensure that immigrants who are otherwise eligible for these tax credits receive them.
Is California Really a High-Tax State?
• By Carl Davis, Eli Byerly-Duke
Key Findings For families of modest means, California is not a high-tax state. California taxes are close to the national average for families in the bottom 80 percent of the income scale. For the bottom 40 percent of families, California taxes are lower than states like Florida and Texas. The highest earners usually pay higher […]
Fairness Matters: A Chart Book on Who Pays State and Local Taxes
• By ITEP Staff
State and local tax codes can do a lot to reduce inequality. But they add to the nation’s growing income inequality problem when they capture a greater share of income from low- or moderate-income taxpayers. These regressive tax codes also result in higher tax rates on communities of color, further worsening racial income and wealth divides.
Corporate Tax Avoidance in the First Five Years of the Trump Tax Law
• By Matthew Gardner, Spandan Marasini, Steve Wamhoff
The Trump tax law overhaul cut the federal corporate income tax rate from 35 percent to 21 percent, but during the first five years it has been in effect, most profitable corporations paid considerably less than that.
Preventing an Overload: How Property Tax Circuit Breakers Promote Housing Affordability
• By Brakeyshia Samms, Carl Davis
Circuit breaker credits are the most effective tool available to promote property tax affordability. These policies prevent a property tax “overload” by crediting back property taxes that go beyond a certain share of income. Circuit breakers intervene to ensure that property taxes do not swallow up an unreasonable portion of qualifying households’ budgets.
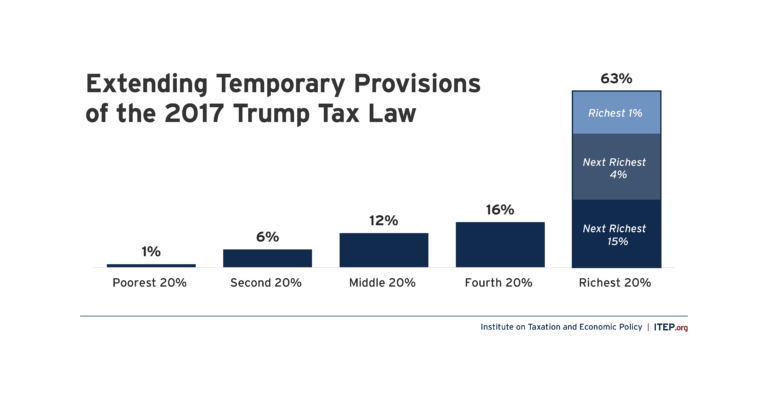
Extending Temporary Provisions of the 2017 Trump Tax Law: National and State-by-State Estimates
• By Joe Hughes, Matthew Gardner, Steve Wamhoff
The push by Congressional Republicans to make the provisions of the 2017 Tax Cuts and Jobs Act permanent would cost nearly $300 billion in the first year and deliver the bulk of the tax benefits to the wealthiest Americans.
Tax Avoidance Continues to Fuel School Privatization Efforts
• By Carl Davis
Wealthy families are overwhelmingly the ones using school voucher tax credits to opt out of paying for public education and other public services and to redirect their tax dollars to private and religious institutions instead. Most of these credits are being claimed by families with incomes over $200,000.
State Child Tax Credits and Child Poverty: A 50-State Analysis
• By Aidan Davis
Regardless of future Child Tax Credit developments at the federal level, state policies can supplement the federal credit to deliver additional benefits to children and families. State credits can be specifically tailored to meet the needs of local populations while also producing long-term benefits for society as a whole
The Geographic Distribution of Extreme Wealth in the U.S.
• By Carl Davis
More than one in four dollars of wealth in the U.S. is held by a tiny fraction of households with net worth over $30 million. Nationally, we estimate that wealth over $30 million per household will reach $26 trillion in 2022 with roughly one-fifth of that amount ($4.5 trillion) held by billionaires.
Creating Racially and Economically Equitable Tax Policy in the South
• By Kamolika Das
The South's negative outcomes on measures of wellbeing are the result of a century and a half of policy choices. Lawmakers have many options available to make concrete improvements to tax policy that would raise more revenue, do so equitably, and generate resources that could improve schools, healthcare, social services, infrastructure, and other public resources.
The Impact of Work From Home on Commercial Property Values and the Property Tax in U.S. Cities
• By ITEP Staff
The fiscal implications of a decline in commercial property values are important because the property tax is the dominant local source of taxes, and commercial property makes up a significant portion of the property base in cities.
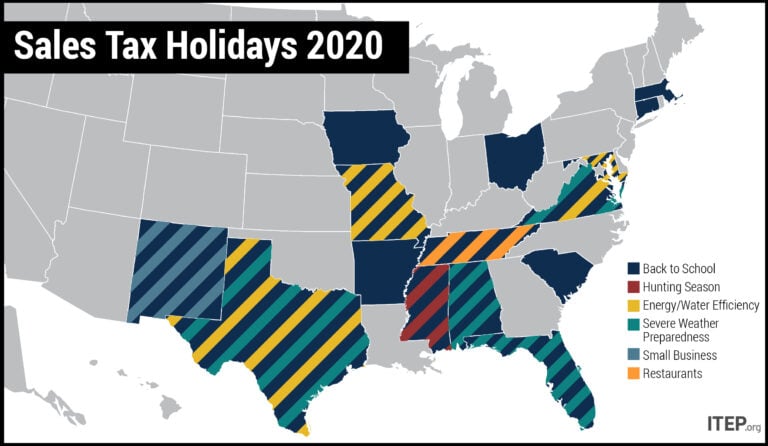
Sales Tax Holidays: An Ineffective Alternative to Real Sales Tax Reform
• By Dylan Grundman O'Neill
Lawmakers in many states have enacted “sales tax holidays” (16 states will hold them in 2020) to provide a temporary break on paying the tax on purchases of clothing, school supplies, and other items. These holidays may seem to lessen the regressive impacts of the sales tax, but their benefits are minimal while their downsides are significant—and amplified in the context of the COVID-19 pandemic. This policy brief looks at sales tax holidays as a…
State Options to Shore up Revenues and Improve Tax Codes amid Pandemic
• By Dylan Grundman O'Neill, Meg Wiehe
The COVID-19 pandemic is an extraordinarily challenging time, as we see harm and struggle affecting the vast majority of our families, businesses, public services, and economic sectors. No one will be unaffected by the crisis, and everyone has a stake in the recovery and faces tough decisions. In the world of state fiscal policy, where revenue shortfalls are likely to be far bigger than can be filled by the initial $150 billion in federal aid…
Institute on Taxation
and Economic Policy
ITEP is a non-profit, non-partisan tax policy organization. We conduct rigorous analyses of tax and economic proposals and provide data-driven recommendations to shape equitable and sustainable tax systems.
Subscribe to ITEP Emails
Tax research and policy news in your inbox.
Promote Fair Tax Policy
Your gift to ITEP promotes tax justice. With your help, we do research that supports taxing millionaires and billionaires, taxing big corporations and raising revenue for the things our people, our communities and our planet need.
Together, we can create a country with more economic justice, more racial justice, more climate justice… and more tax justice.