Arizona
States Should Move Quickly to Chart Their Own Course on SALT Deductions
• By Dylan Grundman O'Neill, Nick Johnson
While a federal SALT cap is hotly debated, capping deductibility at $10,000 was an unambiguously good idea at the state level. States would be smart to stick with the current cap or, better yet, go even farther and repeal SALT deductions outright. Going along with a higher federal SALT cap would double down on a regressive tax cut that will mostly benefit a small number of relatively wealthy state residents and cost states significant revenue.
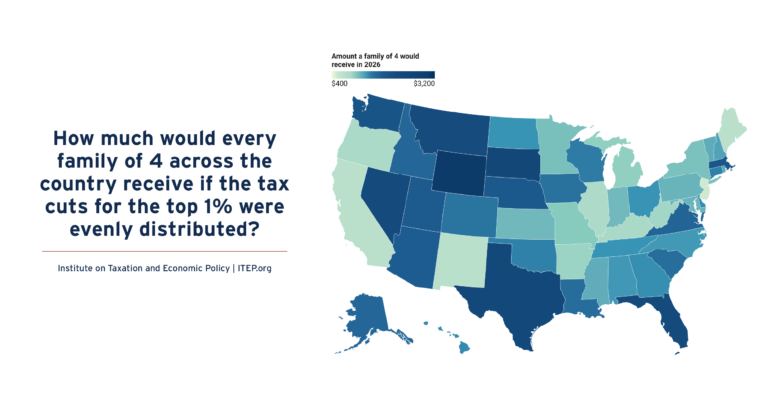
How Much Would Every Family in Every State Get if the Megabill’s Tax Cuts Given to the Rich Had Instead Been Evenly Divided?
• By Michael Ettlinger
If instead of giving $117 billion to the richest 1 percent, that money had been evenly divided among all Americans, we'd each get $343 - or nearly $1,400 for a family of four.
Analysis of Tax Provisions in the Trump Megabill as Signed into Law: National and State Level Estimates
• By Steve Wamhoff, Carl Davis, Joe Hughes, Jessica Vela
President Trump has signed into law the tax and spending “megabill” that largely favors the richest taxpayers and provides working-class Americans with relatively small tax cuts that will in many cases be more than offset by Trump's tariffs.
Trump Megabill Will Give $117 Billion in Tax Cuts to the Top 1% in 2026. How Much In Your State?
• By Michael Ettlinger
The predominant feature of the tax and spending bill working its way through Congress is a massive tax cut for the richest 1 percent — a $114 billion benefit to the wealthiest people in the country in 2026 alone.

How Much Do the Top 1% in Each State Get from the Trump Megabill?
• By Carl Davis
The Senate tax bill under debate right now would bring very large tax cuts to very high-income people. In total, the richest 1 percent would receive $114 billion in tax cuts next year alone. That would amount to nearly $61,000 for each of these affluent households.
Analysis of Tax Provisions in the House Reconciliation Bill: National and State Level Estimates
• By Carl Davis, Jessica Vela, Joe Hughes, Steve Wamhoff
The poorest fifth of Americans would receive 1 percent of the House reconciliation bill's net tax cuts in 2026 while the richest fifth of Americans would receive two-thirds of the tax cuts. The richest 5 percent alone would receive a little less than half of the net tax cuts that year.
Trump 2025 Tax Law: Research and Resources
• By ITEP Staff
Want to know more about the tax and spending megabill that President Trump recently signed into law? We've got you covered.
Trump Administration’s Decision to End Direct File is Another Gift to Big Corporations
• By ITEP Staff
Contact: Jon Whiten (jon@itep.org) According to multiple reports, the Trump administration plans to eliminate the IRS Direct File program, a free electronic system for filing tax returns directly to the agency. Statement from ITEP Executive Director Amy Hanauer “The tax preparation industry has for years lobbied to prevent the IRS from providing a tool to […]
Arizona Daily Star: Trump’s Deportation Net Widens to Migrants with Legal Status, Taxpayers
April 13, 2025
The Trump administration has moved to revoke parole protections issued under President Joe Biden and deport migrants like Doralis, who followed all the rules and used CBP One to enter the U.S. Read more.
IRS Cooperation with ICE Will Damage Public Trust, Putting Tax Revenues in Jeopardy
• By Marco Guzman
Attempts by the Department of Homeland Security to secure private information from the IRS on people who file taxes with an Individual Taxpayer Identification Number is a violation of federal privacy laws that protect taxpayers. It is also a change that could seriously damage public trust in the IRS, which could jeopardize billions of dollars in tax payments by hardworking immigrant families.
Sharp Turn in Federal Policy Brings Significant Risks for State Tax Revenues
• By Carl Davis
Summary The new presidential administration and Congress have indicated that they intend to bring about a dramatic federal retreat in funding for health care, food assistance, education, and other services that will push more of the responsibility for providing these essential services to the states. Meeting these new obligations would be a challenging task for […]
State Rundown 4/3: Amidst Tariff Uncertainty, State Lawmakers Talk Taxes
• By ITEP Staff
While all eyes are on the Trump administration’s tariffs on foreign imports, state lawmakers are moving forward with a mix of deep, regressive tax cuts and progressive revenue raisers.
Tip Exemptions Have No Place in State Income Tax
• By Eli Byerly-Duke, Nick Johnson
Creating a special tax break for tipped income – as at least 20 states are considering this spring – would harm state budgets, encourage tax avoidance, and fail to reach the vast majority of low- and middle-income workers.
Shelter Skelter: How the Educational Choice for Children Act Would Use Tax Avoidance to Fuel School Privatization
• By Carl Davis
The Educational Choice for Children Act of 2025 would ostensibly provide a tax break on charitable donations to organizations that give out private K-12 school vouchers. Most of the so-called “contributions,” however, would be made by wealthy people solely for the tax savings, as those savings would typically be larger than their contributions.
A Revenue Impact Analysis of the Educational Choice for Children Act of 2025
• By Carl Davis
The Educational Choice for Children Act of 2025 would provide donors to nonprofit groups that distribute private K-12 school vouchers with a dollar-for-dollar federal tax credit in exchange for their contributions. In total, the ECCA would reduce federal and state tax revenues by $10.6 billion in 2026 and by $136.3 billion over the next 10 years. Federal tax revenues would decline by $134 billion over 10 years while state revenues would decline by $2.3 billion.
High-Rent, Low-Wealth: Addressing the Racial Wealth Gap through a Federal Renter Credit
• By Brakeyshia Samms, Emma Sifre, Joe Hughes
While the federal tax code has some policies focused on raising income of low earners, it contains fewer provisions designed specifically to address wealth inequality. A renter tax credit offers a simple, administratively practical means of reaching low-wealth populations through the federal tax code without requiring a comprehensive measurement of every household’s wealth.
Turning IRS Agents to Deportation Will Reduce Public Revenues
• By Carl Davis, Jon Whiten
The Trump Administration’s plan to turn IRS agents into deportation agents will result in lower tax collections in addition to the harm done to the families and communities directly affected by deportations.
The (Mostly Untapped) Power of Local Income Taxes
• By Rita Jefferson
Local income taxes can be an important progressive revenue raiser, as they ask more of higher-income households and are connected to ability to pay. They can raise substantial revenue to fund key public services to make cities and regions better off.
State Rundown 1/22: Tax Policy, Affordability, and Where It Misses the Mark
• By ITEP Staff
As state legislative sessions ramp up many lawmakers discuss their prioritization of affordability of necessities like food and housing as they craft their legislative agendas. Arkansas, Mississippi and Utah are looking to reduce or fully exempt groceries from their state sales taxes. Meanwhile, multiple proposals to reduce property taxes are making their way around state […]
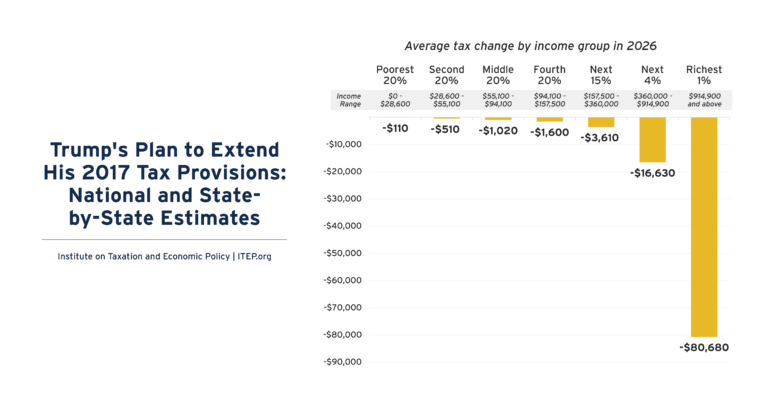
Trump’s Plan to Extend His 2017 Tax Provisions: Updated National and State-by-State Estimates
• By Steve Wamhoff
Trump’s plan to make most of the temporary provisions of his 2017 tax law permanent would disproportionately benefit the richest Americans. This includes all major provisions except the $10,000 cap on deductions for state and local taxes (SALT) paid.
The Pitfalls of Flat Income Taxes
• By Carl Davis, Eli Byerly-Duke
While most states have a graduated rate income tax, some state lawmakers have recently become enamored with the idea of moving toward flat rate taxes instead. What’s the difference? And are states well served by the transition? In short: A flat tax is one where each taxpayer pays the same percentage of their income whereas […]
State Rundown 11/20: Some Budgets and Tax Proposals Fail to Defy Gravity, Fall Short
• By ITEP Staff
This week, there are high-profile budget and tax debates at both the state and local levels. The Louisiana legislature continues to debate Gov. Jeff Landry’s deeply regressive tax package in a special session focused on replacing corporate and personal income tax revenue with additional sales taxes, but some efforts to find offsets for the cuts […]
On Election Day, Voters Across the Country Chose to Invest in Their States & Communities
• By Kamolika Das
On election day, voters across the country — in states red and blue and communities rural and urban — approved a wide range of state and local ballot measures on taxation and public investment. The success of these measures clearly shows that voters are willing to invest in public priorities that feel tangible and close to home.
State Rundown 11/07: Election Week and New Special Sessions
• By ITEP Staff
Tax policy results are mixed across the country as many voters weigh in on state and local ballot measures. For example, Washington state voted to maintain its new progressive tax on capital gains; Georgia voters capped growth in property tax assessments; Illinois voters approved a call for a millionaires’ tax; North Dakota voters rejected property […]
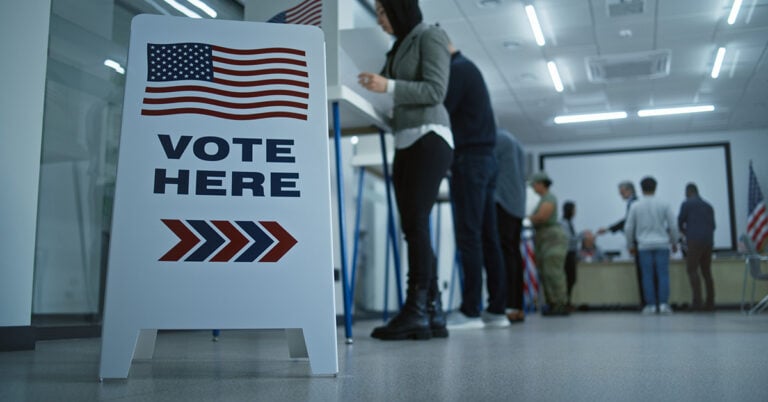
2024 State Tax Ballot Questions: Voters to Weigh in on Tax Changes Big and Small
• By Jon Whiten
As we approach November’s election, voters in several states will be weighing in on tax policy changes. The outcomes will impact the equity of state and local tax systems and the adequacy of the revenue those systems are able to raise to fund public services.
Institute on Taxation
and Economic Policy
ITEP is a non-profit, non-partisan tax policy organization. We conduct rigorous analyses of tax and economic proposals and provide data-driven recommendations to shape equitable and sustainable tax systems.
Subscribe to ITEP Emails
Tax research and policy news in your inbox.
Promote Fair Tax Policy
Your gift to ITEP promotes tax justice. With your help, we do research that supports taxing millionaires and billionaires, taxing big corporations and raising revenue for the things our people, our communities and our planet need.
Together, we can create a country with more economic justice, more racial justice, more climate justice… and more tax justice.