Publications
Taxing Advertising Would Modernize State Sales Tax Bases for the Information Age
• By Nick Johnson
Most states questionably exempt advertising from sales taxes. States that extend their sales taxes to advertising and/or enact an excise tax stand to raise billions in revenue while correcting a structural bias in their tax codes that implicitly subsidizes some of the most profitable corporations in human history.
Re-Examining 529 Plans: Stopping State Subsidies to Private Schools After New Trump Tax Law
• By Miles Trinidad, Nick Johnson
The 2025 federal tax law risks making 529 plans more costly for states by increasing tax avoidance and allowing wealthy families to use these funds for private and religious K-12 schools.
States Should Move Quickly to Chart Their Own Course on SALT Deductions
• By Dylan Grundman O'Neill, Nick Johnson
While a federal SALT cap is hotly debated, capping deductibility at $10,000 was an unambiguously good idea at the state level. States would be smart to stick with the current cap or, better yet, go even farther and repeal SALT deductions outright. Going along with a higher federal SALT cap would double down on a regressive tax cut that will mostly benefit a small number of relatively wealthy state residents and cost states significant revenue.
Analysis of Tax Provisions in the Trump Megabill as Signed into Law: National and State Level Estimates
• By Steve Wamhoff, Carl Davis, Joe Hughes, Jessica Vela
President Trump has signed into law the tax and spending “megabill” that largely favors the richest taxpayers and provides working-class Americans with relatively small tax cuts that will in many cases be more than offset by Trump's tariffs.
Analysis of Tax Provisions in the House Reconciliation Bill: National and State Level Estimates
• By Carl Davis, Jessica Vela, Joe Hughes, Steve Wamhoff
The poorest fifth of Americans would receive 1 percent of the House reconciliation bill's net tax cuts in 2026 while the richest fifth of Americans would receive two-thirds of the tax cuts. The richest 5 percent alone would receive a little less than half of the net tax cuts that year.
Trump 2025 Tax Law: Research and Resources
• By ITEP Staff
Want to know more about the tax and spending megabill that President Trump recently signed into law? We've got you covered.
Sharp Turn in Federal Policy Brings Significant Risks for State Tax Revenues
• By Carl Davis
Summary The new presidential administration and Congress have indicated that they intend to bring about a dramatic federal retreat in funding for health care, food assistance, education, and other services that will push more of the responsibility for providing these essential services to the states. Meeting these new obligations would be a challenging task for […]
High-Rent, Low-Wealth: Addressing the Racial Wealth Gap through a Federal Renter Credit
• By Brakeyshia Samms, Emma Sifre, Joe Hughes
While the federal tax code has some policies focused on raising income of low earners, it contains fewer provisions designed specifically to address wealth inequality. A renter tax credit offers a simple, administratively practical means of reaching low-wealth populations through the federal tax code without requiring a comprehensive measurement of every household’s wealth.
The (Mostly Untapped) Power of Local Income Taxes
• By Rita Jefferson
Local income taxes can be an important progressive revenue raiser, as they ask more of higher-income households and are connected to ability to pay. They can raise substantial revenue to fund key public services to make cities and regions better off.
Tax Payments by Undocumented Immigrants
• By ITEP Staff
Undocumented immigrants paid $96.7 billion in federal, state, and local taxes in 2022. Providing access to work authorization for undocumented immigrants would increase their tax contributions both because their wages would rise and because their rates of tax compliance would increase.
Improving Refundable Tax Credits by Making Them Immigrant-Inclusive
• By Emma Sifre, Marco Guzman
Undocumented immigrants who work and pay taxes but don't have a valid Social Security number for either themselves or their children are excluded from federal EITC and CTC benefits. Fortunately, several states have stepped in to ensure undocumented immigrants are not left behind by the gaps in the federal EITC and CTC. State lawmakers should continue to ensure that immigrants who are otherwise eligible for these tax credits receive them.
Local Mansion Taxes: Building Stronger Communities with Progressive Taxes on High-Value Real Estate
• By Andrew Boardman
More than one dozen cities and counties levy progressive taxes on high-price real estate transactions — sometimes called mansion taxes — and over a dozen more are considering such policies. By asking buyers and sellers with greater financial means to contribute more to the common good, these policies are equipping communities with resources to make progress on critical challenges of local and national concern.
Preventing an Overload: How Property Tax Circuit Breakers Promote Housing Affordability
• By Brakeyshia Samms, Carl Davis
Circuit breaker credits are the most effective tool available to promote property tax affordability. These policies prevent a property tax “overload” by crediting back property taxes that go beyond a certain share of income. Circuit breakers intervene to ensure that property taxes do not swallow up an unreasonable portion of qualifying households’ budgets.
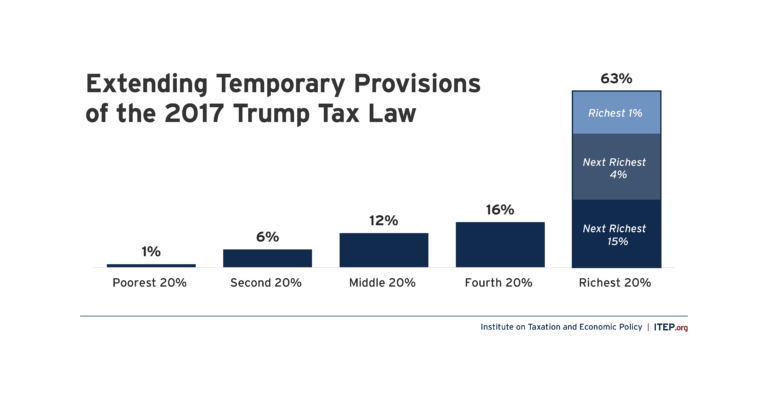
Extending Temporary Provisions of the 2017 Trump Tax Law: National and State-by-State Estimates
• By Joe Hughes, Matthew Gardner, Steve Wamhoff
The push by Congressional Republicans to make the provisions of the 2017 Tax Cuts and Jobs Act permanent would cost nearly $300 billion in the first year and deliver the bulk of the tax benefits to the wealthiest Americans.
State Child Tax Credits and Child Poverty: A 50-State Analysis
• By Aidan Davis
Regardless of future Child Tax Credit developments at the federal level, state policies can supplement the federal credit to deliver additional benefits to children and families. State credits can be specifically tailored to meet the needs of local populations while also producing long-term benefits for society as a whole
The Geographic Distribution of Extreme Wealth in the U.S.
• By Carl Davis
More than one in four dollars of wealth in the U.S. is held by a tiny fraction of households with net worth over $30 million. Nationally, we estimate that wealth over $30 million per household will reach $26 trillion in 2022 with roughly one-fifth of that amount ($4.5 trillion) held by billionaires.
Boosting Incomes and Improving Tax Equity with State Earned Income Tax Credits in 2022
• By Aidan Davis
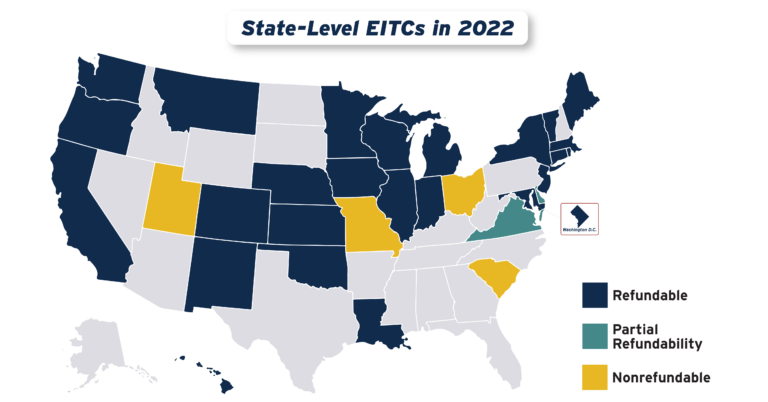
States continued their recent trend of advancing EITCs in 2022, with nine states plus the District of Columbia either creating or improving their credits. Utah enacted a 15 percent nonrefundable EITC, while the District of Columbia, Hawaii, Illinois, Maine, Vermont and Virginia expanded existing credits. Meanwhile, Connecticut, New York and Oregon provided one-time boosts to their EITC-eligible populations.
Boosting Incomes and Improving Tax Equity with State Earned Income Tax Credits in 2021
• By Aidan Davis
The EITC benefits low-income people of all races and ethnicities. But it is particularly impactful in historically excluded Black and Hispanic communities where discrimination in the labor market, inequitable educational systems, and countless other inequities have relegated a disproportionate share of people to low-wage jobs.
State Income Taxes and Racial Equity: Narrowing Racial Income and Wealth Gaps with State Personal Income Taxes
• By Carl Davis, Jessica Schieder, Marco Guzman
10 state personal income tax reforms that offer the most promising routes toward narrowing racial income and wealth gaps through the tax code.
Not Worth Its SALT: Tax Cut Proposal Overwhelmingly Benefits Wealthy, White Households
• By Carl Davis, ITEP Staff, Jessica Schieder
A previous ITEP analysis showed the lopsided distribution of SALT cap repeal by income level. The vast majority of families would not benefit financially from repeal and most of the tax cuts would flow to families with incomes above $200,000. This report builds on that work by using a mix of tax return and survey data within our microsimulation tax model to estimate the distribution of SALT cap repeal across race and ethnicity. It shows…
Taxes and Racial Equity: An Overview of State and Local Policy Impacts
• By ITEP Staff
Historic and current injustices, both in public policy and in broader society, have resulted in vast disparities in income and wealth across race and ethnicity. Employment discrimination has denied good job opportunities to people of color. An uneven system of public education funding advantages wealthier white people and produces unequal educational outcomes. Racist policies such as redlining and discrimination in lending practices have denied countless Black families the opportunity to become homeowners or business owners,…
State Taxation of Capital Gains: The Folly of Tax Cuts & Case for Proactive Reforms
• By Marco Guzman
The federal tax system and every state treat income from capital gains more favorably than income from work. Preferential capital gains tax treatment includes exclusions and seldom-discussed provisions like deferral and stepped-up basis, as well as more direct tax subsidies for profits realized from local investments and, in some instances, from investments around the world. This policy brief explains state capital gains taxation, examines the flaws in state capital gains tax breaks, and proposes reform…
Boosting Incomes and Improving Tax Equity with State Earned Income Tax Credits in 2020
• By Aidan Davis
The Earned Income Tax Credit (EITC) is a policy designed to bolster the incomes of low-wage workers and offset some of the taxes they pay, providing the opportunity for families struggling to afford the high cost of living to step up and out of poverty toward meaningful economic security. The federal EITC has kept millions of Americans out of poverty since its enactment in the mid-1970s. Over the past several decades, the effectiveness of the…
State Options to Shore up Revenues and Improve Tax Codes amid Pandemic
• By Dylan Grundman O'Neill, Meg Wiehe
The COVID-19 pandemic is an extraordinarily challenging time, as we see harm and struggle affecting the vast majority of our families, businesses, public services, and economic sectors. No one will be unaffected by the crisis, and everyone has a stake in the recovery and faces tough decisions. In the world of state fiscal policy, where revenue shortfalls are likely to be far bigger than can be filled by the initial $150 billion in federal aid…
State Itemized Deductions: Surveying the Landscape, Exploring Reforms
• By Carl Davis
State itemized deductions are generally patterned after federal law, though nearly every state makes significant changes to the menu of deductions available or the extent to which those deductions are allowed. This report summarizes the key details of each state’s itemized deduction policies and discusses various options for reforming those deductions with a focus on lessening their regressive impact and reducing their cost to state budgets.
Institute on Taxation
and Economic Policy
ITEP is a non-profit, non-partisan tax policy organization. We conduct rigorous analyses of tax and economic proposals and provide data-driven recommendations to shape equitable and sustainable tax systems.
Subscribe to ITEP Emails
Tax research and policy news in your inbox.
Promote Fair Tax Policy
Your gift to ITEP promotes tax justice. With your help, we do research that supports taxing millionaires and billionaires, taxing big corporations and raising revenue for the things our people, our communities and our planet need.
Together, we can create a country with more economic justice, more racial justice, more climate justice… and more tax justice.