Publications
State-by-State Tax Expenditure Reports
• By ITEP Staff
Below is a list of tax expenditure reports published in the states.
Linking to Tipped and Overtime Income Deductions Would Worsen State Shortfalls, Do Little to Help Workers
• By Neva Butkus, Galen Hendricks
State deductions for tips and overtime are not only ineffective at supporting working-class people, it will come at a substantial cost to state budgets.
The Wealth Proceeds Tax: A Simple Way for States to Tax the Wealthy
• By Sarah Austin, Carl Davis
Taxing the proceeds generated by wealth through a new Wealth Proceeds Tax is a simple way for states to raise billions in new revenue and improve the fairness of their tax systems.
States Should Move Quickly to Chart Their Own Course on SALT Deductions
• By Dylan Grundman O'Neill, Nick Johnson
While a federal SALT cap is hotly debated, capping deductibility at $10,000 was an unambiguously good idea at the state level. States would be smart to stick with the current cap or, better yet, go even farther and repeal SALT deductions outright. Going along with a higher federal SALT cap would double down on a regressive tax cut that will mostly benefit a small number of relatively wealthy state residents and cost states significant revenue.
Analysis of Tax Provisions in the Trump Megabill as Signed into Law: National and State Level Estimates
• By Steve Wamhoff, Carl Davis, Joe Hughes, Jessica Vela
President Trump has signed into law the tax and spending “megabill” that largely favors the richest taxpayers and provides working-class Americans with relatively small tax cuts that will in many cases be more than offset by Trump's tariffs.
Analysis of Tax Provisions in the House Reconciliation Bill: National and State Level Estimates
• By Carl Davis, Jessica Vela, Joe Hughes, Steve Wamhoff
The poorest fifth of Americans would receive 1 percent of the House reconciliation bill's net tax cuts in 2026 while the richest fifth of Americans would receive two-thirds of the tax cuts. The richest 5 percent alone would receive a little less than half of the net tax cuts that year.
Trump 2025 Tax Law: Research and Resources
• By ITEP Staff
Want to know more about the tax and spending megabill that President Trump recently signed into law? We've got you covered.
A Revenue Analysis of Worldwide Combined Reporting in the States
• By Carl Davis, Matthew Gardner, Michael Mazerov
Universal adoption of mandatory worldwide combined reporting would boost state corporate income tax revenues by roughly 14 percent. Thirty-eight states and the District of Columbia would experience revenue increases totaling $19.1 billion.
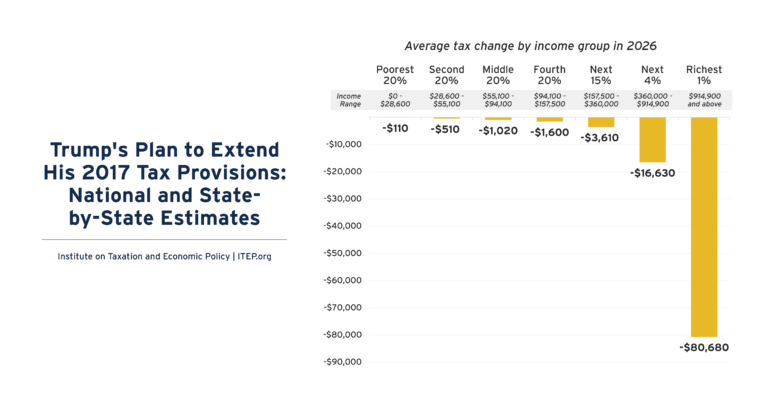
Trump’s Plan to Extend His 2017 Tax Provisions: Updated National and State-by-State Estimates
• By Steve Wamhoff
Trump’s plan to make most of the temporary provisions of his 2017 tax law permanent would disproportionately benefit the richest Americans. This includes all major provisions except the $10,000 cap on deductions for state and local taxes (SALT) paid.

Extending Temporary Provisions of the 2017 Trump Tax Law: Updated National and State-by-State Estimates
• By Steve Wamhoff
The TCJA Permanency Act would make permanent the provisions of the Tax Cuts and Jobs Act of 2017 that are set to expire at the end of 2025. The legislation would disproportionately benefit the richest Americans. Below are graphics for each state that show the effects of making TCJA permanent across income groups. See ITEP’s […]
Tax Payments by Undocumented Immigrants
• By ITEP Staff
Undocumented immigrants paid $96.7 billion in federal, state, and local taxes in 2022. Providing access to work authorization for undocumented immigrants would increase their tax contributions both because their wages would rise and because their rates of tax compliance would increase.
Improving Refundable Tax Credits by Making Them Immigrant-Inclusive
• By Emma Sifre, Marco Guzman
Undocumented immigrants who work and pay taxes but don't have a valid Social Security number for either themselves or their children are excluded from federal EITC and CTC benefits. Fortunately, several states have stepped in to ensure undocumented immigrants are not left behind by the gaps in the federal EITC and CTC. State lawmakers should continue to ensure that immigrants who are otherwise eligible for these tax credits receive them.
The Estate Tax is Irrelevant to More Than 99 Percent of Americans
• By Steve Wamhoff
The federal estate tax has reached historic lows. In 2019, only 8 of every 10,000 people who died left an estate large enough to trigger the tax. Legislative changes under presidents of both parties have increased the basic exemption from the estate tax over the past 20 years. This has cut the share of adults leaving behind taxable estates down from more than 2 percent to well under 1 percent.
Far From Radical: State Corporate Income Taxes Already Often Look Beyond the Water’s Edge
• By Carl Davis, Matthew Gardner
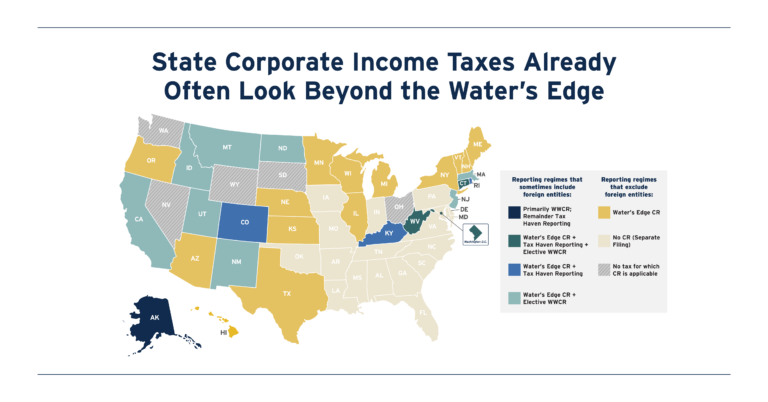
State lawmakers are increasingly interested in reforming their corporate tax bases to start from a comprehensive measure of worldwide profit. This provides a more accurate, and less gameable, starting point for calculating profits subject to state corporate tax. Mandating this kind of filing system, known as worldwide combined reporting (WWCR), would be transformative, as it would all but eliminate state corporate tax avoidance done through the artificial shifting of profits into low-tax countries.
Extending Temporary Provisions of the 2017 Trump Tax Law: National and State-by-State Estimates
• By Joe Hughes, Matthew Gardner, Steve Wamhoff
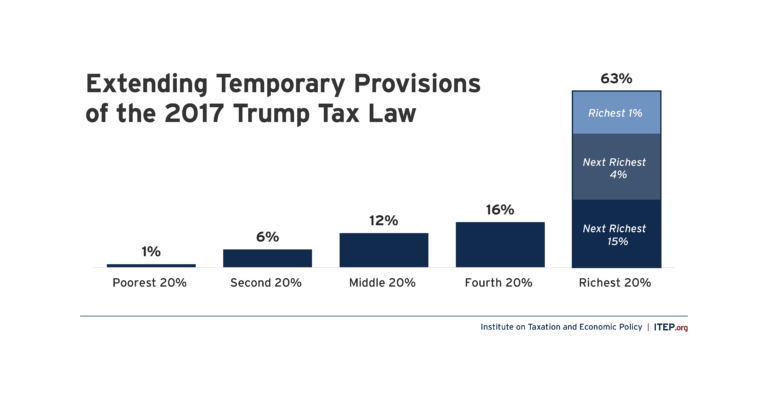
The push by Congressional Republicans to make the provisions of the 2017 Tax Cuts and Jobs Act permanent would cost nearly $300 billion in the first year and deliver the bulk of the tax benefits to the wealthiest Americans.
State Child Tax Credits and Child Poverty: A 50-State Analysis
• By Aidan Davis
Regardless of future Child Tax Credit developments at the federal level, state policies can supplement the federal credit to deliver additional benefits to children and families. State credits can be specifically tailored to meet the needs of local populations while also producing long-term benefits for society as a whole
Effects of the President’s Capital Gains and Dividends Tax Proposals by State
• By ITEP Staff, Matthew Gardner, Steve Wamhoff
President Biden’s proposal to eliminate the lower income tax rate on capital gains (profits from selling assets) and stock dividends for millionaires would affect less than half of one percent (0.4 percent) of U.S. taxpayers if it goes into effect in 2022. The share of taxpayers affected would be less than 1 percent in every state.
Taxes and Racial Equity: An Overview of State and Local Policy Impacts
• By ITEP Staff
Historic and current injustices, both in public policy and in broader society, have resulted in vast disparities in income and wealth across race and ethnicity. Employment discrimination has denied good job opportunities to people of color. An uneven system of public education funding advantages wealthier white people and produces unequal educational outcomes. Racist policies such as redlining and discrimination in lending practices have denied countless Black families the opportunity to become homeowners or business owners,…
Comparing Flat-Rate Income Tax Options for Alaska
• By Carl Davis
Alaska lawmakers are facing an unprecedented fiscal crisis. The state is more dependent than any other on oil tax and royalty revenues but declines in oil prices and production levels have sapped much of the vitality of these revenue sources. One way of diversifying the state’s revenue stream and narrowing the yawning gap between state revenues and expenses would be to reinstitute a statewide personal income tax. Alaska previously levied such a tax until 1980.…
State Taxation of Capital Gains: The Folly of Tax Cuts & Case for Proactive Reforms
• By Marco Guzman
The federal tax system and every state treat income from capital gains more favorably than income from work. Preferential capital gains tax treatment includes exclusions and seldom-discussed provisions like deferral and stepped-up basis, as well as more direct tax subsidies for profits realized from local investments and, in some instances, from investments around the world. This policy brief explains state capital gains taxation, examines the flaws in state capital gains tax breaks, and proposes reform…
State Options to Shore up Revenues and Improve Tax Codes amid Pandemic
• By Dylan Grundman O'Neill, Meg Wiehe
The COVID-19 pandemic is an extraordinarily challenging time, as we see harm and struggle affecting the vast majority of our families, businesses, public services, and economic sectors. No one will be unaffected by the crisis, and everyone has a stake in the recovery and faces tough decisions. In the world of state fiscal policy, where revenue shortfalls are likely to be far bigger than can be filled by the initial $150 billion in federal aid…
State Itemized Deductions: Surveying the Landscape, Exploring Reforms
• By Carl Davis
State itemized deductions are generally patterned after federal law, though nearly every state makes significant changes to the menu of deductions available or the extent to which those deductions are allowed. This report summarizes the key details of each state’s itemized deduction policies and discusses various options for reforming those deductions with a focus on lessening their regressive impact and reducing their cost to state budgets.
The Case for Extending State-Level Child Tax Credits to Those Left Out: A 50-State Analysis
• By Aidan Davis, Meg Wiehe
As of 2017, 11.5 million children in the United States were living in poverty. A national, fully-refundable Child Tax Credit (CTC) would effectively address persistently high child poverty rates at the national and state levels. The federal CTC in its current form falls short of achieving this goal due to its earnings requirement and lack of full refundability. Fortunately, states have options to make state-level improvements in the absence of federal policy change. A state-level…
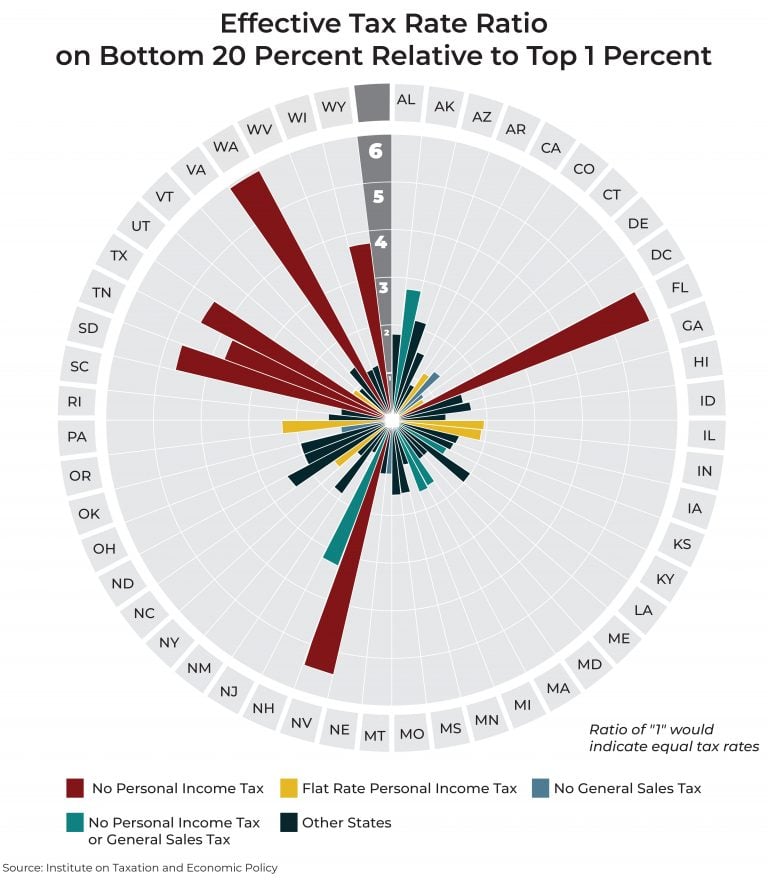
Fairness Matters: A Chart Book on Who Pays State and Local Taxes
• By ITEP Staff
There is significant room for improvement in state and local tax codes. State tax codes are filled with top-heavy exemptions and deductions and often fail to tax higher incomes at higher rates. States and localities have come to rely too heavily on regressive sales taxes that fail to reflect the modern economy. And overall tax collections are often inadequate in the short-run and unsustainable in the long-run. These types of shortcomings provide compelling reason to…

Taxing Cannabis
• By Carl Davis, Misha Hill, Richard Phillips
State policy toward cannabis is evolving rapidly. While much of the debate around legalization has rightly focused on potential health and criminal justice impacts, legalization also has revenue implications for state and local governments that choose to regulate and tax cannabis sales. This report describes the various options for structuring state and local taxes on cannabis and identifies approaches currently in use. It also undertakes an in-depth exploration of state cannabis tax revenue performance and…
Institute on Taxation
and Economic Policy
ITEP is a non-profit, non-partisan tax policy organization. We conduct rigorous analyses of tax and economic proposals and provide data-driven recommendations to shape equitable and sustainable tax systems.
Subscribe to ITEP Emails
Tax research and policy news in your inbox.
Promote Fair Tax Policy
Your gift to ITEP promotes tax justice. With your help, we do research that supports taxing millionaires and billionaires, taxing big corporations and raising revenue for the things our people, our communities and our planet need.
Together, we can create a country with more economic justice, more racial justice, more climate justice… and more tax justice.