Reports
429 posts
State Income Tax Subsidies for Seniors
• By Carl Davis, Eli Byerly-Duke
State governments provide a wide array of tax subsidies to their older residents. But too many of these carveouts focus on predominately wealthy and white seniors, all while the cost climbs.
Effects of President Biden’s Proposal to Expand the Child Tax Credit
• By Joe Hughes
In his latest budget proposal, President Biden proposes enhancing the Child Tax Credit (CTC) based on the temporary credit that was in effect for 2021 as part of the American Rescue Plan Act. In this report we analyze how that proposal would help children and families.
Revenue-Raising Proposals in President Biden’s Fiscal Year 2024 Budget Plan
• By Steve Wamhoff
President Biden’s latest budget proposal includes trillions of dollars of new revenue that would be paid by the richest Americans, both directly through increases in personal income, Medicare and estate taxes, and indirectly through increases in corporate income taxes.
State Child Tax Credits and Child Poverty: A 50-State Analysis
• By Aidan Davis
Regardless of future Child Tax Credit developments at the federal level, state policies can supplement the federal credit to deliver additional benefits to children and families. State credits can be specifically tailored to meet the needs of local populations while also producing long-term benefits for society as a whole
The Geographic Distribution of Extreme Wealth in the U.S.
• By Carl Davis
More than one in four dollars of wealth in the U.S. is held by a tiny fraction of households with net worth over $30 million. Nationally, we estimate that wealth over $30 million per household will reach $26 trillion in 2022 with roughly one-fifth of that amount ($4.5 trillion) held by billionaires.
Unfinished Tax Reform: Corporate Minimum Taxes
• By Steve Wamhoff
While the Inflation Reduction Act's corporate minimum tax is a huge improvement in our tax system, implementing the global corporate minimum tax would improve it much more. And if other governments implement the global minimum tax, the United States will have an even stronger interest in joining them to ensure that new revenue collected from American corporations flows to the U.S. rather than to other countries.
National and State-by-State Estimates of Two Approaches to Expanding the Child Tax Credit
• By Emma Sifre, Joe Hughes, Steve Wamhoff
The Romney Child Tax Credit plan would leave a quarter of children worse off compared to current law and help half as many low-income children as the 2021 expansion of the credit.
Creating Racially and Economically Equitable Tax Policy in the South
• By Kamolika Das
The South's negative outcomes on measures of wellbeing are the result of a century and a half of policy choices. Lawmakers have many options available to make concrete improvements to tax policy that would raise more revenue, do so equitably, and generate resources that could improve schools, healthcare, social services, infrastructure, and other public resources.
Revenue-Raising Proposals in President Biden’s Fiscal Year 2023 Budget Plan
• By Steve Wamhoff
President Biden's latest budget plan includes proposals that would raise $2.5 trillion in new revenue. While many of these reforms appeared in his previous budget, some of them are brand new, such as his proposal to prevent basis-shifting in partnerships and his Billionaires Minimum Income Tax.
What the Biden Administration Can Do on Its Own, Without Congress, to Fix the Tax Code
• By Steve Wamhoff
The Biden administration has several options to address tax reform even when Congress is unable or unwilling to help.
State-by-State Estimates of Sen. Rick Scott’s “Skin in the Game” Proposal
• By Steve Wamhoff
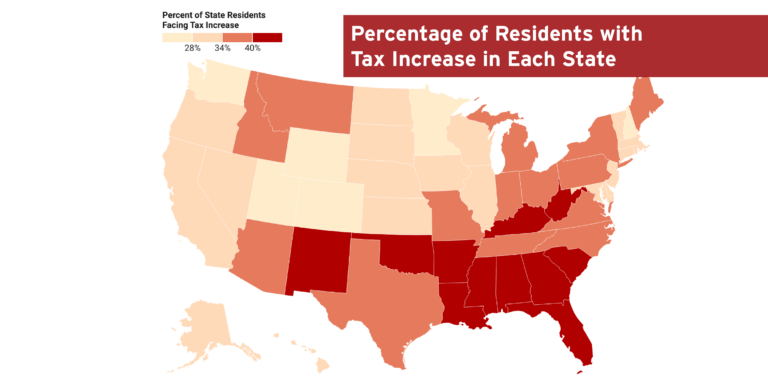
A proposal from Sen. Rick Scott would increase taxes for more than 35% of Americans, with the poorest fifth of Americans paying 34% of the tax increase.
Federal EITC Enhancements Help More Than One in Three Young Workers
• By Aidan Davis
More than one in three young adults would benefit from workers without children being eligible to receive the federal EITC. This policy change would bolster young adults’ economic security.
Revenue-Raising Proposals in the Evolving Build Back Better Debate
• By Steve Wamhoff
The United States needs to raise more tax revenue to fund investments in the American people. This revenue can be obtained with reforms that would require the richest and wealthiest Americans to pay their fair share to support the society that makes their fortunes possible.
Analysis of the House of Representatives’ Build Back Better Legislation
• By Carl Davis, Steve Wamhoff
If the bill becomes law, in 2022 federal taxes would go up for the average taxpayer among the richest one percent and down for the average taxpayer in other income groups.
The Impact of Work From Home on Commercial Property Values and the Property Tax in U.S. Cities
• By ITEP Staff
The fiscal implications of a decline in commercial property values are important because the property tax is the dominant local source of taxes, and commercial property makes up a significant portion of the property base in cities.
State Income Taxes and Racial Equity: Narrowing Racial Income and Wealth Gaps with State Personal Income Taxes
• By Carl Davis, Jessica Schieder, Marco Guzman
10 state personal income tax reforms that offer the most promising routes toward narrowing racial income and wealth gaps through the tax code.
Repealing the SALT Cap Would Wipe Out Revenue Raised by the House Ways and Means Bill’s Income Tax Provisions
• By Steve Wamhoff
There are several ways that the House leadership could avoid this problem. One approach is for lawmakers to replace the SALT cap with a different kind of limit on tax breaks for the rich that actually raises revenue and avoids disfavoring some states compared to others as the SALT cap does. ITEP has suggested a way to do this.
Tax Changes in the House Ways and Means Committee Build Back Better Bill
• By ITEP Staff, Matthew Gardner, Steve Wamhoff
This report finds that the vast majority of these tax increases would be paid by the richest 1 percent of Americans and foreign investors. The bill’s most significant tax cuts -- expansions of the Child Tax Credit (CTC) and Earned Income Tax Credit (EITC) -- would more than offset the tax increases for the average taxpayer in all income groups except for the richest 5 percent.
Why Congress Should Reform the Federal Corporate Income Tax
• By Joe Hughes, Steve Wamhoff
It is reasonable for corporations (and, indirectly, their shareholders) to pay taxes to support the government investments that make their profits possible, such as the highways that facilitate the movement of goods and people, the education and health care systems that provide a productive workforce, the legal system and the protection of property, all of which are vital to commerce. Corporate tax avoidance allows wealthy and powerful individuals to reap enormous benefits from these investments…
Options to Reduce the Revenue Loss from Adjusting the SALT Cap
• By Carl Davis, ITEP Staff, Matthew Gardner, Steve Wamhoff
If lawmakers are unwilling to replace the SALT cap with a new limit on tax breaks that raises revenue, then any modification they make to the cap in the current environment will lose revenue and make the federal tax code less progressive. Given this, lawmakers should choose a policy option that loses as little revenue as possible and that does the smallest amount of damage possible to the progressivity of the federal tax code.
Corporate Tax Avoidance Under the Tax Cuts and Jobs Act
• By ITEP Staff, Matthew Gardner, Steve Wamhoff
Thirty-nine profitable corporations in the S&P 500 or Fortune 500 paid no federal income tax from 2018 through 2020, the first three years that the Tax Cuts and Jobs Act (TCJA) was in effect. Besides the 39 companies that paid nothing over three years, an additional 73 profitable corporations paid less than half the statutory corporate income tax rate of 21 percent established under TCJA. As a group, these 73 corporations paid an effective federal…
Not Worth Its SALT: Tax Cut Proposal Overwhelmingly Benefits Wealthy, White Households
• By Carl Davis, ITEP Staff, Jessica Schieder
A previous ITEP analysis showed the lopsided distribution of SALT cap repeal by income level. The vast majority of families would not benefit financially from repeal and most of the tax cuts would flow to families with incomes above $200,000. This report builds on that work by using a mix of tax return and survey data within our microsimulation tax model to estimate the distribution of SALT cap repeal across race and ethnicity. It shows…
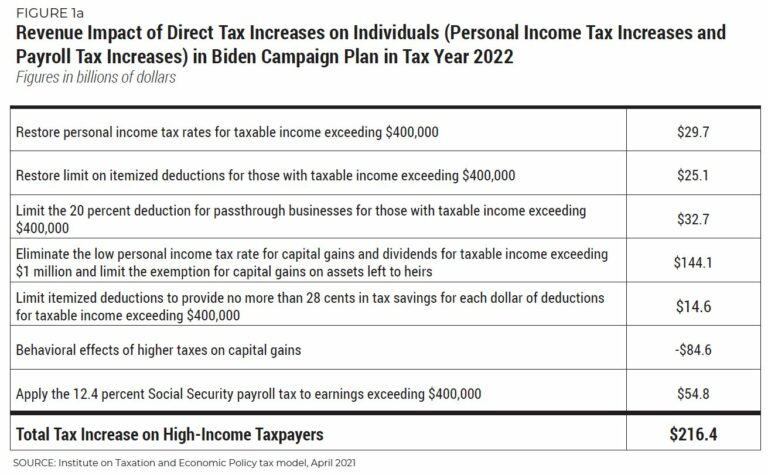
National and State-by-State Estimates of President Biden’s Campaign Proposals for Revenue
• By ITEP Staff, Matthew Gardner, Steve Wamhoff
During his presidential campaign, Joe Biden proposed to change the tax code to raise revenue directly from households with income exceeding $400,000. More precisely, Biden proposed to raise personal income taxes on unmarried individuals and married couples with taxable income exceeding $400,000, and he also proposed to raise payroll taxes on individual workers with earnings exceeding $400,000. Just 2 percent of taxpayers would see a direct tax hike (an increase in either personal income taxes,…
A Proposal to Simplify President Biden’s Campaign Plan for Personal Income Taxes and Replace the Cap on SALT Deductions
• By Steve Wamhoff
In this paper, we describe a tax policy idea that would simplify the proposals President Biden presented during his campaign to raise personal income taxes for those with annual incomes greater than $400,000. Our proposal would replace the cap on state and local tax (SALT) deductions with a broader limit on tax breaks for the rich that would raise more revenue than the personal income tax hikes that Biden proposed during his campaign. Our proposal…
55 Corporations Paid $0 in Federal Taxes on 2020 Profits
• By Matthew Gardner, Steve Wamhoff
At least 55 of the largest corporations in America paid no federal corporate income taxes in their most recent fiscal year despite enjoying substantial pretax profits in the United States. This continues a decades-long trend of corporate tax avoidance by the biggest U.S. corporations, and it appears to be the product of long-standing tax breaks preserved or expanded by the 2017 tax law as well as the CARES Act tax breaks enacted in the spring…
Institute on Taxation
and Economic Policy
ITEP is a non-profit, non-partisan tax policy organization. We conduct rigorous analyses of tax and economic proposals and provide data-driven recommendations to shape equitable and sustainable tax systems.
Subscribe to ITEP Emails
Tax research and policy news in your inbox.
Promote Fair Tax Policy
Your gift to ITEP promotes tax justice. With your help, we do research that supports taxing millionaires and billionaires, taxing big corporations and raising revenue for the things our people, our communities and our planet need.
Together, we can create a country with more economic justice, more racial justice, more climate justice… and more tax justice.